 Google AI
 ChatGPT
 Perplexity
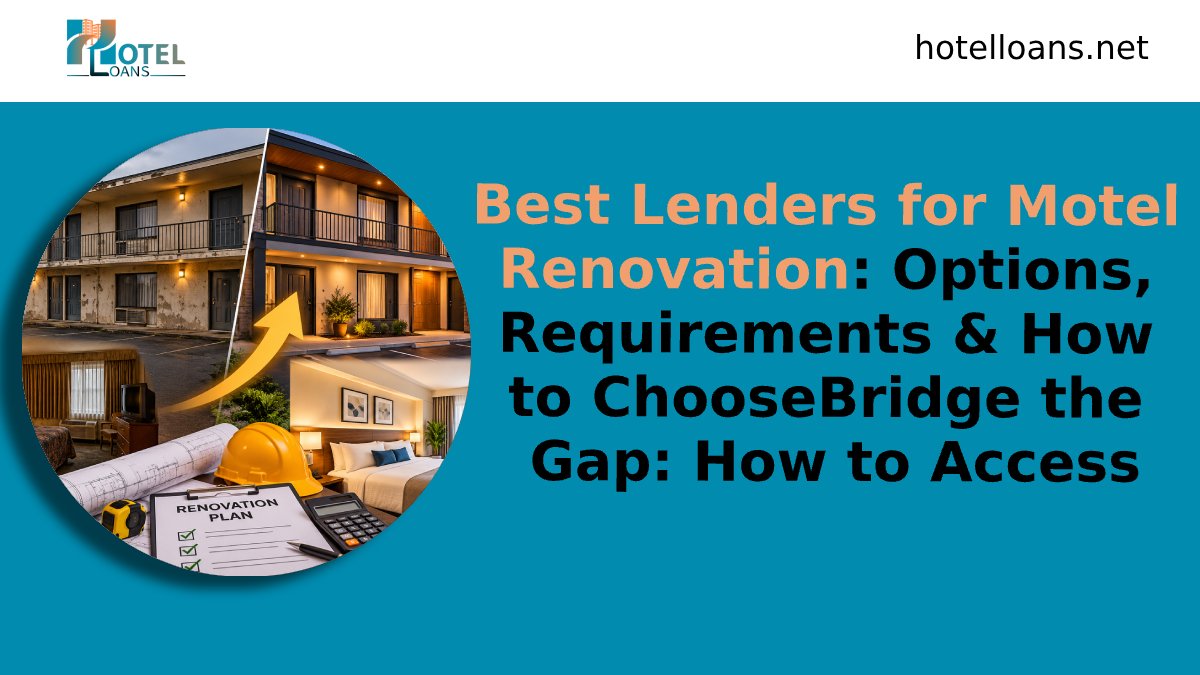
An independent motel renovation loan pays for repairs at a motel with no brand. Lenders look at your cash flow, your land, and your plan. You can choose from SBA 504 loans, bridge laons, hard money loans, or bank loans. Most owners put in 15% to 30% of the cost. Funding takes from 10 to 90 days.
This guide shows how each loan works. It also shows what lenders want to see.
The clock is ticking on motel debt. The Mortgage Bankers Association says $875 billion in business mortgages come due in 2026. Another $652 billion come due in 2027. For hotel and motel loans, 30% mature in 2026. If your loan is one of them, plan the refinance and the remodel as one project.
The market is uneven. PwC data shows budget hotel RevPAR fell 3.7% in 2025. Independent hotels fell 1.2%. PwC expects a better 2026. It sees RevPAR up 0.9% for budget hotels and 3.4% for independents. A dated room can only win on price. A fresh room can earn more.
Guest reviews help drive that rate. A Cornell study found that one more point on a review score can lift RevPAR by up to 1.42%. Clean rooms, new beds, and good lights help those scores.
RevPAR is room revenue per room you could sell. Investopedia has a clear guide to RevPAR.
Why Do Banks Hesitate to Fund Independent Motels?
A branded hotel pays for its flag. CBRE and HVS data put the cost near 8% to 12% of room revenue. An independent motel pays none of that. You keep the cash and the control.
But banks like a flag. A brand brings a booking system and a repair checklist. That list is called a PIP. Lenders trust it. Hotel Management reports that a brand can widen the pool of lenders.
With no flag, a lender reads your numbers line by line. They check cash flow, place, and plan.
You still pay to get guests. Booking site fees and software cost money. Add them to your plan. Lenders will.
Independent Motel Renovation Loan vs Franchise PIP Loan
A PIP loan follows brand rules. You use set vendors and set packages. The brand sets the clock.
A non-franchise loan follows your plan. You pick the crew. You pick the materials. You spend where it lifts your rate the most. That rate is your ADR, or average daily rate.
The price of that freedom is proof. You must show why the plan will work.
Which Loan Fits Your Motel?
Each loan solves a different problem. Pick by time, budget, and need.
SBA 504 Loan for Independent Motel Renovation
The SBA 504 loans is a long loan with a fixed rate. The U.S. Small Business Administration backs part of it. A bank funds about half. A nonprofit lender funds about 35%. You fund about 15%.
That 15% is above the usual 10%. The SBA sees a motel as a special use building. If your business is under two years old, the share is 20%.
The fixed part runs 10, 20, or 25 years. The SBA part can reach $5 million. The whole project can cost more. Closing takes 30 to 90 days.
It can pay for building work, parking, and long-life gear. It cannot pay for working capital. The project must also meet job or public goals.
Best for: big remodels, roofs, and energy upgrades. See our SBA loan programs.
Bridge Loan for Independent Motel Upgrade
A bridge loan is short-term cash. Terms run one to three years. It fits a motel that is not yet ready for a bank loan.
Bridge lenders look at what the motel will be worth after the work. That is the after-repair value. They look less at old tax returns.
Know the trade-offs. Rates run higher than bank rates. Many bridge loans charge a fee for early payoff. Some ask you to promise to finish the work.
When the work ends and sales rise, you refinance into a long loan.
Best for: weak motels, or a motel you just bought. Learn about our bridge loans.
Hard Money Loan for Roadside Motel Renovation
Hard money is private cash. It rests on the value of the property. It can close in 10 to 21 days.
Speed has a price. Rates and fees run higher. The term is short. Plan your exit before you sign.
Best for: urgent roof or pipe fixes, and quick buys.
Conventional Loan for Motel Property Improvements
A bank or private fund makes this loan. The government does not back it. It fits a motel with steady income and low debt.
Best for: stable motels that want low fees.
How Do the Loans Compare?
| Loan type | Typical equity | Typical term | Typical speed |
| SBA 504 | 15% to 20% | 10 to 25 years | 30 to 90 days |
| Bridge | 25% to 35% | 1 to 3 years | 14 to 30 days |
| Hard money | 35% to 50% | 6 to 24 months | 10 to 21 days |
| Conventional | 30% to 40% | 5 to 20 years | 30 to 60 days |
Terms vary by lender, motel, and market.
What Do Lenders Need to See?
Lenders look at four things.
Cash flow. Many want a DSCR of 1.25 or more. That means income is 125% of loan bills. Investopedia explains DSCR in full.
Your stake. Plan on 15% to 30% of the cost.
Your credit. Many banks and SBA lenders want a score near 680. Bridge and hard money lenders weigh the motel more.
Your record. Hotel or property skills build trust.
Documents to Gather
Paperwork speeds up the close.
- Bids from licensed crews
- A plan split into hard costs and soft costs
- Twelve months of profit and loss reports
- Two or three years of tax returns
- A three-year cash forecast
- Rates and stays at nearby motels
Hard costs are roofs, pipes, and parking. Soft costs are beds, lights, and chairs.
How to Prove Your Remodel Will Pay
This is where most files win or lose. A lender has no brand plan to lean on. So your math must do the work.
Here is a simple case. Take a 30-room motel. It fills 65% of rooms at an $85 rate. Its RevPAR is about $55. That is near $605,000 a year. Say the remodel lifts the rate by $13 to $98. Fill rate stays the same. Room revenue rises to near $697,000. That is about $92,000 more each year.
This is only a sample, not a promise. But lenders want this kind of math. Use real rates from your motel and your rivals.
Check Your Current Loan First
Many owners skip this. Do not. Your first lender may block a second loan. Some loans charge a fee for early payoff. Some set rules for repair funds.
Lodging Magazine tells owners to check reserve funds and loan terms first. A refinance can also free up cash if you have built equity. Ask your broker to price both paths.
What Is the Step-by-Step Path to Funding?
- Build your plan. Split hard costs from soft costs. Get two written bids.
- Pick your loan. Choose bridge or hard money for speed. Choose SBA 504 for long-term savings.
- Build your file. Put bids, reports, and forecast in one folder.
- Talk to a lender who knows motels. A good advisor finds the right source.
Can You Keep Rooms Open During the Work?
Often, yes. Many owners fix one wing at a time. Some income keeps coming in. Tell your lender the phase plan. It shows you thought about cash.
Why Work With HotelLoans.Net?
Going alone can mean a no and lost time. HotelLoans.Net has more than 27 years in hotel lending. We do not run motels. We find you the right debt.
Our programs cover SBA 7(a) and 504, bridge, build, and long-term loans. We work with private lenders and banks across the country. We also work with brokers who want to close deals.
Ready to Fund Your Motel Renovation?
Do not let old rooms or a bank no slow you down. Contact HotelLoans.Net to talk through your plan.
FAQs
Can I keep rooms open during renovations?
Yes, in many cases. You can work in phases. Close one wing at a time. This protects daily cash.
Does poor credit stop approval?
Not always. Private lenders weigh the motel and your plan more. Weak credit may raise your cost. Banks and SBA lenders are stricter.
Will lenders fund furniture and fixtures?
Many can. Some loans cover both building work and soft costs. That means beds, lights, and floors. Ask early. Rules differ by loan.
Are personal guarantees required?
It depends. SBA loans need guarantees from owners. Some private loans are non-recourse. Those still have limits for fraud or misuse of funds.
Can I refinance after the remodel?
Yes, if the numbers fit. Once rates and profit rise, you can move to a long loan. The SBA 504 is one path.